Government Schemes for Female Entrepreneurs in India 2026: Women Business Loan, Subsidy और Startup Schemes
Written By Dilshad AhmadPublished: 06 October 2026 • 11:08 PM IST
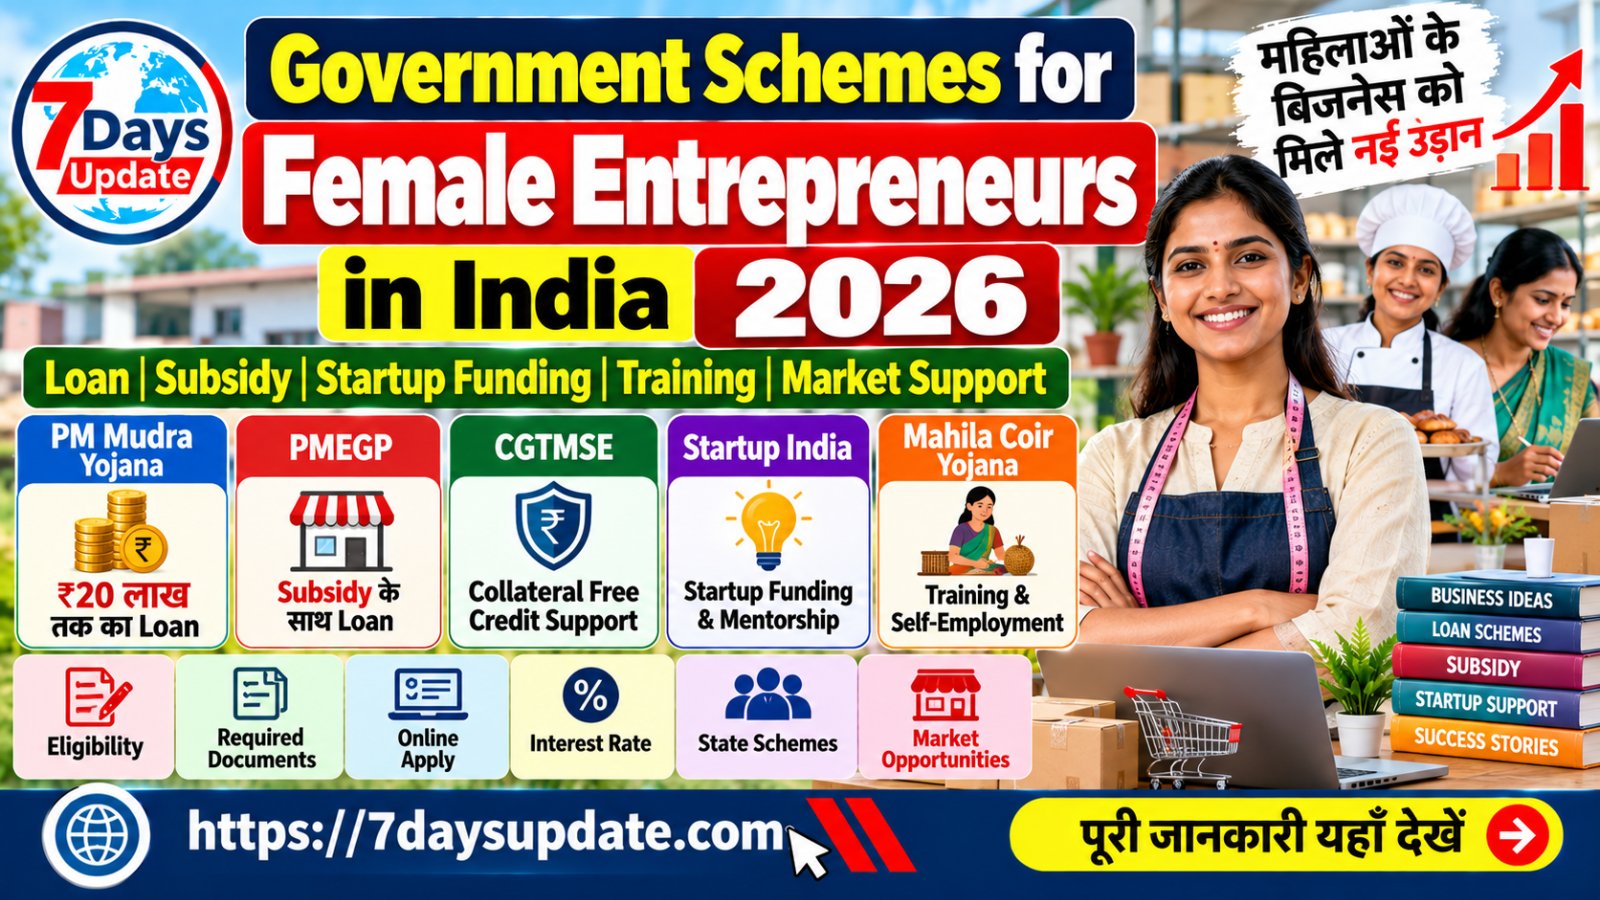
भारत में अपना business शुरू करने या existing business को expand करने वाली महिलाओं के लिए Government की कई अलग-अलग schemes और support mechanisms उपलब्ध हैं। इनमें कुछ schemes सीधे loan देती हैं, कुछ में subsidy या credit guarantee का support मिलता है, जबकि कुछ programmes training, startup funding, mentorship और market access में मदद करते हैं।
Government Schemes for Female Entrepreneurs in India 2026 की इस guide में हम Women Business Loan, PM Mudra Yojana, PMEGP, CGTMSE, Startup India, Mahila Coir Yojana, women startup funding, eligibility, documents, online application और Stand-Up India की current status को एक जगह समझेंगे।
Female Entrepreneurs के लिए Government Schemes कौन-कौन सी हैं?
महिला entrepreneurs के लिए सबसे उपयोगी central-level options को broadly इस प्रकार समझा जा सकता है:
| Scheme / Support | मुख्य फायदा | किसके लिए उपयोगी |
|---|---|---|
| PM Mudra Yojana | Collateral-free business credit | Micro & small businesses |
| PMEGP | Credit-linked subsidy | New micro enterprise |
| CGTMSE | Credit guarantee support | Women-owned MSEs |
| Startup India | Startup ecosystem, funding & mentorship | Innovative startups |
| Mahila Coir Yojana | Training & self-employment support | Women artisans in coir sector |
| State Women/Startup Schemes | State-specific funding, subsidy & support | State-based entrepreneurs |
1. PM Mudra Yojana for Women Entrepreneurs
Pradhan Mantri Mudra Yojana (PMMY) महिलाओं के लिए सबसे relevant business-credit options में से एक है। यह exclusively women-only scheme नहीं है, लेकिन women-owned and operated enterprises ने PMMY lending में बड़ी participation दिखाई है।
Current PMMY structure में चार categories हैं:
- Shishu: ₹50,000 तक
- Kishor: ₹50,000 से अधिक और ₹5 lakh तक
- Tarun: ₹5 lakh से अधिक और ₹10 lakh तक
- Tarun Plus: ₹10 lakh से अधिक और ₹20 lakh तक, eligible previous Tarun borrowers के लिए
PMMY में collateral की requirement नहीं होती। Loan का उपयोग eligible micro business की term-loan और working-capital requirements के लिए किया जा सकता है। Poultry, dairy और beekeeping जैसी agriculture-allied activities भी scheme framework में शामिल हैं। 1
Women के लिए Mudra Loan में क्या फायदा है?
महिला entrepreneur अपना नया business शुरू करने या existing micro business को बढ़ाने के लिए PMMY के तहत eligible lender से loan के लिए apply कर सकती है। Final loan amount और terms bank या अन्य participating lending institution की assessment पर निर्भर करते हैं।
Government के 2023 data के अनुसार PMMY के तहत ₹10 lakh तक के sanctioned loans में 68% loans women-owned and operated enterprises को दिए गए थे। 2
2. PMEGP for Women Entrepreneurs
अगर महिला entrepreneur नया micro enterprise शुरू करना चाहती हैं और loan के साथ credit-linked subsidy चाहती हैं, तो Prime Minister's Employment Generation Programme (PMEGP) महत्वपूर्ण option है।
PMEGP में women को Special Category में रखा गया है। Current MSME information के अनुसार new projects में women beneficiaries के लिए own contribution 5% है और subsidy urban area में 25% तथा rural area में 35% है। 3
| Project | Maximum Admissible Cost | Women Subsidy |
|---|---|---|
| Manufacturing | ₹50 lakh | 25% Urban / 35% Rural |
| Business / Service | ₹20 lakh | 25% Urban / 35% Rural |
PMEGP एक subsidy-linked scheme है, इसलिए इसे simple business loan और PMMY से अलग समझना चाहिए।
3. CGTMSE Support for Women-Owned Businesses
Credit Guarantee Scheme through CGTMSE उन businesses के लिए महत्वपूर्ण हो सकती है जिन्हें collateral-free institutional credit की जरूरत है।
Current MSME Annual Report 2025-26 के अनुसार CGTMSE में women-owned MSEs के लिए 10% concession in annual guarantee fee उपलब्ध है। Women-led enterprises के लिए guarantee coverage को 90% तक बढ़ाया गया है। 4
यह समझना जरूरी है कि CGTMSE खुद सामान्य अर्थ में applicant को सीधे cash loan नहीं देता। यह eligible credit facility के लिए lender को credit guarantee support देता है। Loan application संबंधित Member Lending Institution के माध्यम से होती है।
4. Startup India for Women Entrepreneurs
अगर business traditional small shop या micro enterprise के बजाय innovative startup है, तो Startup India ecosystem अधिक relevant हो सकता है।
Startup India के तहत DPIIT-recognised startups के लिए विभिन्न initiatives जैसे Startup India Seed Fund Scheme, MAARG mentorship, Investor Connect, Fund of Funds और National Startup Awards उपलब्ध ecosystem का हिस्सा हैं। 5
महिला founder के लिए इसका फायदा केवल loan तक सीमित नहीं है। Startup stage के अनुसार funding, mentorship, incubation, investor access और market ecosystem भी महत्वपूर्ण हो सकते हैं।
5. Startup India Seed Fund Scheme
अगर महिला entrepreneur ने technology या innovation-based startup शुरू किया है, तो Startup India ecosystem की Seed Fund Scheme relevant हो सकती है।
इस initiative का उद्देश्य proof of concept, prototype development, product trials, market entry और commercialization जैसी शुरुआती जरूरतों के लिए financial assistance उपलब्ध कराना है। 6
यह सामान्य दुकान या traditional business के लिए automatic business loan नहीं है। Startup की nature और scheme eligibility अलग से देखी जाती है।
6. Mahila Coir Yojana
Mahila Coir Yojana Coir sector में महिलाओं के self-employment और skill development पर focused programme है।
MSME की scheme information के अनुसार इसमें rural women artisans को coir-related activities में training और stipend support के साथ self-employment opportunities से जोड़ने का उद्देश्य है। 7
अगर किसी महिला का business coconut-producing region और coir products से संबंधित है, तो यह general business loan schemes की तुलना में अधिक targeted option हो सकता है।
7. Women Entrepreneurs के लिए Udyam Registration
Udyam Registration स्वयं कोई loan या subsidy scheme नहीं है, लेकिन women-owned MSME के लिए बहुत important business registration है।
Official Udyam portal के अनुसार registration free, online और paperless है। Registration के बाद permanent Udyam Registration Number और online certificate मिलता है। 8
8. Women-Owned MSMEs के लिए Government Procurement Support
Government support केवल loan तक सीमित नहीं है। Women-owned micro and small enterprises के लिए public procurement ecosystem में भी special support है।
MSME Ministry के अनुसार Central Ministries, Departments और CPSEs की annual procurement में women-owned MSEs से कम से कम 3% procurement का mandate Public Procurement Policy में शामिल किया गया है। 10
इसका मतलब यह है कि eligible women-owned MSMEs के लिए Government market में products/services बेचने का एक additional opportunity channel हो सकता है।
9. Women Entrepreneurs के लिए Credit Guarantee का फायदा
अगर किसी woman-owned MSE को business expansion के लिए bank finance चाहिए और collateral की समस्या है, तो credit guarantee ecosystem useful हो सकता है।
Current CGTMSE framework में women-owned MSEs को guarantee fee concession और enhanced guarantee coverage का benefit दिया गया है। 11
यह benefit lender के माध्यम से credit facility से जुड़ता है; इसे direct cash subsidy नहीं समझना चाहिए।
10. Jan Samarth Portal से Women Business Loan Options
Jan Samarth Portal एक national credit-linked Government schemes portal है। इसमें अलग-अलग sectors और beneficiary requirements से जुड़ी कई credit-linked schemes onboarded हैं।
Official information के अनुसार PMMY और PMEGP सहित कई credit-linked Government schemes Jan Samarth पर available हैं। Portal applicant को eligibility और credit application journey में मदद करता है। 12
इसलिए महिला entrepreneur को अलग-अलग websites पर random loan links खोजने के बजाय पहले official Government portals check करना चाहिए।
Women Entrepreneurs के लिए Loan और Subsidy में क्या अंतर है?
| Support | क्या मिलता है? | Repayment? |
|---|---|---|
| Business Loan | Credit | हाँ |
| PMEGP Subsidy | Margin Money Subsidy | Loan component की repayment होती है |
| CGTMSE | Credit Guarantee | Underlying loan repay करना होता है |
| Startup Funding | Scheme-specific financial support | Instrument पर निर्भर |
Female Entrepreneur के लिए कौन-सी Scheme बेहतर है?
यह पूरी तरह business की nature पर निर्भर करता है। एक simple comparison:
- छोटी दुकान / service business: PM Mudra Yojana useful हो सकती है।
- नया manufacturing/service micro enterprise + subsidy: PMEGP देखना चाहिए।
- Existing MSE को collateral-free credit चाहिए: CGTMSE-backed lending relevant हो सकती है।
- Innovative startup: Startup India ecosystem और Seed Fund जैसे options देखें।
- Coir/coconut-based rural business: Mahila Coir Yojana relevant हो सकती है।
- Government को products/services बेचने वाला MSME: Public Procurement benefits देखें।
Women Business Loan के लिए कौन-कौन से Documents चाहिए?
Exact documents scheme और lender के अनुसार अलग हो सकते हैं। सामान्य तौर पर महिला entrepreneur को निम्न documents तैयार रखने चाहिए:
- Aadhaar Card
- PAN Card
- Address Proof
- Passport-size Photograph
- Bank Account Details
- Business Address/Proof
- Udyam Registration, जहां applicable हो
- Business Plan / Project Report
- Existing business के financial records, जहां applicable हो
- Category certificate, यदि किसी special category benefit का दावा किया जा रहा हो
- Startup recognition documents, जहां applicable हो
Women Entrepreneur Loan Apply करने से पहले क्या तैयार करें?
- Business idea को स्पष्ट करें।
- Total project cost calculate करें।
- अपने contribution की राशि तय करें।
- Expected monthly sales और expenses का realistic estimate बनाएं।
- Loan repayment capacity calculate करें।
- Udyam Registration की जरूरत हो तो official portal से registration करें।
- Relevant Government scheme identify करें।
- Official portal या participating lender से application करें।
क्या महिलाओं को Government से Free Business Loan मिलता है?
नहीं, सामान्य रूप से Government business loan को "free money" नहीं समझना चाहिए।
Mudra जैसी schemes में loan repay करना होता है। PMEGP में eligible project के लिए subsidy component हो सकता है, लेकिन project financing का पूरा amount free grant नहीं होता।
इसी तरह CGTMSE credit guarantee है, direct free cash assistance नहीं।
क्या बिना Collateral Women Business Loan मिल सकता है?
कुछ Government-backed credit frameworks collateral-free lending को support करते हैं। PMMY में collateral requirement नहीं है, जबकि CGTMSE eligible MSE credit facilities के लिए guarantee support प्रदान करता है। 13
फिर भी bank की credit assessment, business viability, repayment capacity और अन्य applicable conditions लागू हो सकती हैं।
Stand-Up India Scheme 2026 की Current Status
Stand-Up India को 5 April 2016 को SC/ST और women entrepreneurs को greenfield enterprises के लिए ₹10 lakh से ₹1 crore तक composite loans उपलब्ध कराने के उद्देश्य से शुरू किया गया था।
लेकिन Department of Financial Services की current information के अनुसार original Stand-Up India scheme की अवधि 31 March 2025 तक थी। FY 2025-26 Budget में 5 lakh first-time women, SC और ST entrepreneurs के लिए अगले पांच वर्षों में ₹2 crore तक term loans वाली एक नई scheme की घोषणा की गई थी; DFS page पर इसे उस समय under preparation बताया गया है। 14
इसलिए readers को किसी पुराने Stand-Up India application link पर blindly भेजने के बजाय latest official Government notification check करने की सलाह देनी चाहिए।
Women Entrepreneurs के लिए State Government Schemes
Central Government schemes के अलावा लगभग हर State में women entrepreneurs के लिए अलग-अलग startup policies, women development schemes, self-help group programmes, interest subsidy, capital subsidy, training और market support programmes हो सकते हैं।
इनका नाम और eligibility राज्य के अनुसार काफी अलग होती है। उदाहरण के लिए Startup India की current ecosystem information में कई States/UTs की अलग startup policies listed हैं। 15
इसलिए अगर महिला entrepreneur उत्तर प्रदेश, बिहार, राजस्थान, महाराष्ट्र, मध्य प्रदेश, कर्नाटक या किसी अन्य State में business शुरू करना चाहती है, तो Central schemes के साथ उस State की current MSME/Startup/Women Development policy भी check करनी चाहिए।
Women Entrepreneurs के लिए Training और Mentorship
Business शुरू करने में केवल loan पर्याप्त नहीं होता। Accounting, digital marketing, GST, customer acquisition, pricing, inventory, online selling और business management जैसी skills भी जरूरी हैं।
Startup India ecosystem में MAARG mentorship और विभिन्न entrepreneurship initiatives available हैं। Startup India का TEJAS initiative भी youth, women, students और first-time founders को district-level entrepreneurship ecosystem से जोड़ने पर focus करता है। 16
महिला Entrepreneur के लिए Government Scheme चुनने का आसान तरीका
| आपकी जरूरत | पहले क्या देखें? |
|---|---|
| ₹50,000 तक छोटा business | Mudra Shishu |
| ₹50,000–₹5 lakh | Mudra Kishor |
| ₹5–₹10 lakh | Mudra Tarun / applicable alternatives |
| ₹10–₹20 lakh और previous Tarun repayment | Mudra Tarun Plus |
| New business + subsidy | PMEGP |
| Collateral-free MSE credit | CGTMSE-backed lending |
| Innovation/startup | Startup India ecosystem |
| Coir business | Mahila Coir Yojana |
Government Schemes for Female Entrepreneurs 2026: FAQs
महिलाओं के लिए सबसे अच्छी Government Business Loan Scheme कौन-सी है?
एक ही scheme सभी महिलाओं के लिए best नहीं है। Small business के लिए PMMY, subsidy-linked new enterprise के लिए PMEGP, collateral-free MSE credit के लिए CGTMSE-backed lending और innovative startup के लिए Startup India ecosystem अधिक relevant हो सकता है।
क्या महिलाओं को Mudra Loan में special benefit मिलता है?
PMMY women-only scheme नहीं है, लेकिन women-owned and operated enterprises की बड़ी participation है और eligible women entrepreneurs PMMY के तहत apply कर सकती हैं।
महिलाओं के लिए PMEGP subsidy कितनी है?
Current PMEGP structure में women Special Category में आती हैं। New projects के लिए subsidy rate urban area में 25% और rural area में 35% है, जबकि beneficiary contribution 5% है। 17
क्या महिला को ₹20 lakh का Mudra Loan मिल सकता है?
PMMY में maximum limit ₹20 lakh है, लेकिन ₹10 lakh से अधिक और ₹20 lakh तक का Tarun Plus loan eligible entrepreneurs के लिए है जिन्होंने previous Tarun loan successfully repay किया है। 18
क्या Government महिलाओं को बिना repayment वाला business loan देती है?
सामान्य business loan schemes को free money नहीं समझना चाहिए। Loan repay करना होता है। कुछ schemes में subsidy या guarantee support अलग से उपलब्ध हो सकता है।
क्या Udyam Registration महिलाओं के लिए free है?
हाँ। Official Udyam portal registration को free और paperless बताता है। 19
क्या women entrepreneurs को Government tender में फायदा मिलता है?
Women-owned MSEs के लिए Central Government procurement policy में minimum 3% annual procurement target का provision है। 20
क्या Stand-Up India अभी 2026 में apply की जा सकती है?
Original Stand-Up India scheme की अवधि 31 March 2025 तक थी। नई first-time entrepreneur scheme की Budget announcement हुई थी, लेकिन application status के लिए latest official Government notification देखना जरूरी है। 21
Official Websites और Useful Links
| PM Mudra Yojana | Official DFS PMMY Page |
| PMEGP | Official MSME PMEGP Information |
| Udyam Registration | Official Udyam Portal |
| Startup India | Official Startup India Portal |
| Jan Samarth | Official Jan Samarth Portal |
| CGTMSE | Official CGTMSE Website |
निष्कर्ष
भारत में female entrepreneurs के लिए Government support केवल एक single women loan scheme तक सीमित नहीं है। PM Mudra Yojana, PMEGP, CGTMSE, Startup India, Mahila Coir Yojana, Udyam Registration, Government procurement support और State-level startup policies अलग-अलग जरूरतों को address करते हैं।
इसलिए business शुरू करने से पहले यह देखना ज्यादा महत्वपूर्ण है कि आपकी जरूरत loan, subsidy, credit guarantee, training, startup funding या market access में से किस category में आती है।
सबसे जरूरी बात यह है कि application केवल official Government portal या authorised lending institution के माध्यम से करें। किसी agent द्वारा “100% loan guarantee”, “free ₹20 lakh”, “Government से direct cash” या “बिना documents तुरंत loan” जैसे claims पर भरोसा न करें।